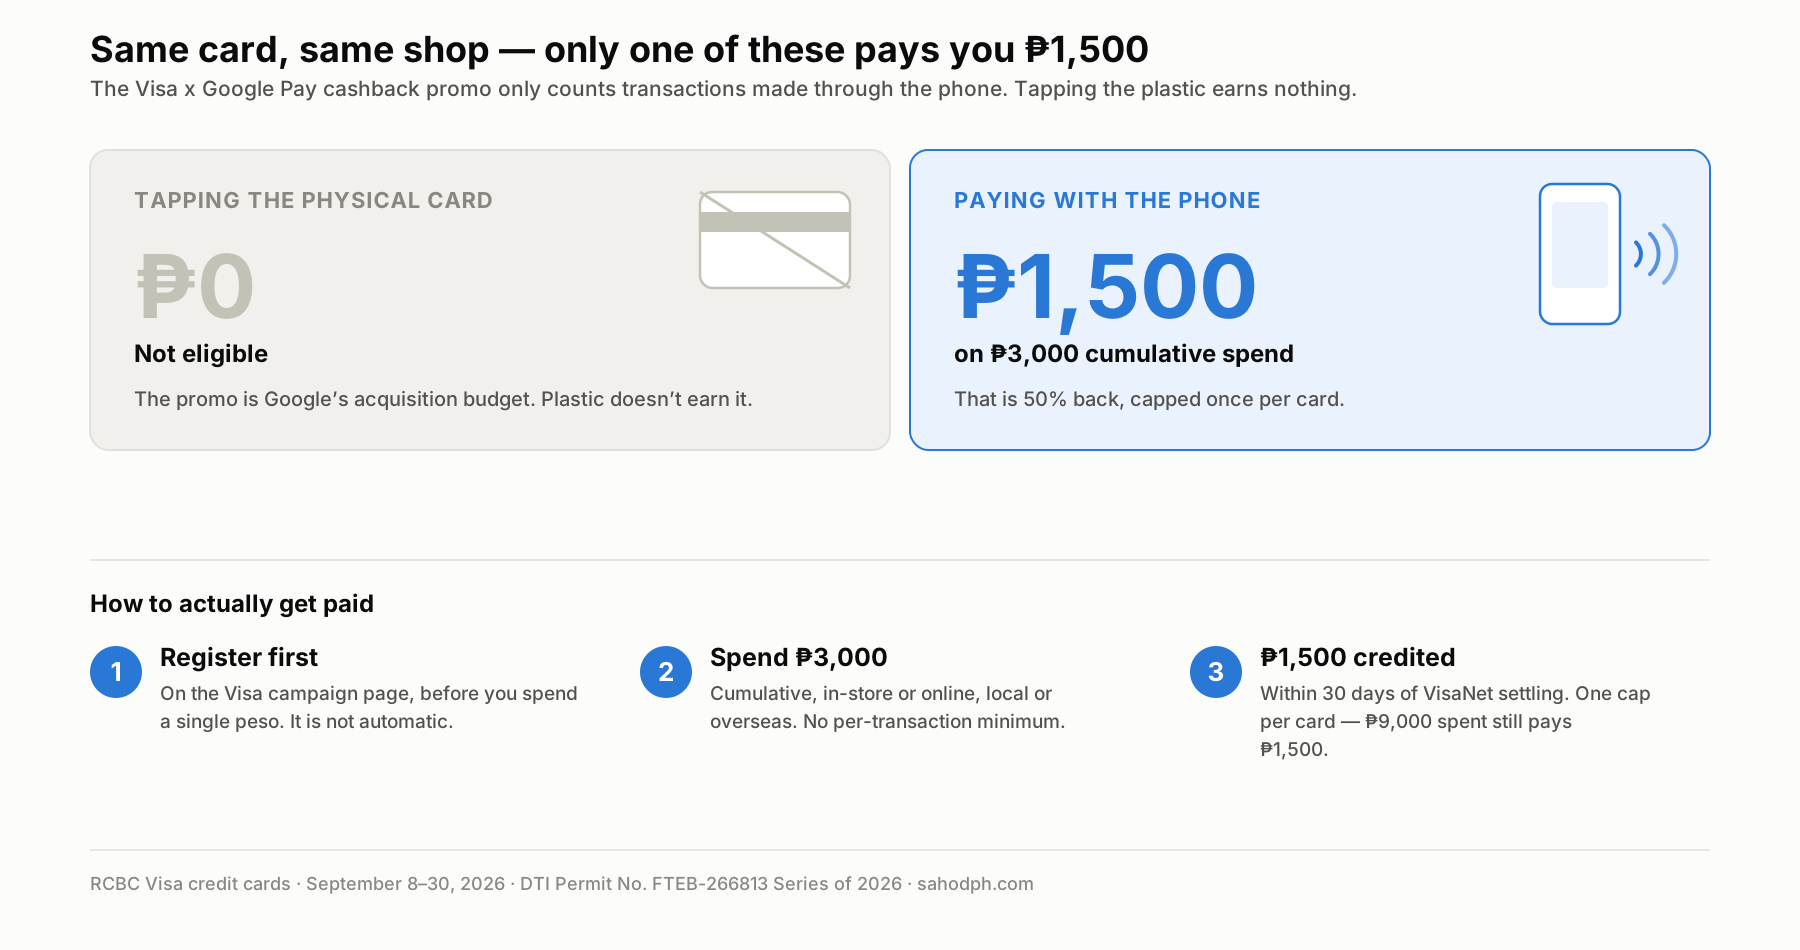
A 50% cashback promo usually means one of two things: the fine print eats it, or you misread the headline. This one is real, and the math is genuinely as good as it sounds — ₱1,500 back on ₱3,000 of spend, running until September 30, 2026.
But there is a step that decides whether you get paid, and it happens before you spend a single peso. Miss it and you'll hit ₱3,000, wait 30 days, and get nothing.
The mechanics
RCBC is running the promo with Visa under DTI Permit No. FTEB-266813, Series of 2026.
| Details |
|---|
| Promo period | September 8–30, 2026 |
| Cashback | ₱1,500 per card, once — this is a cap, not a rate |
| Required spend | ₱3,000 cumulative |
| Minimum per transaction | None |
| Eligible cards | RCBC Visa credit cards, active and in good standing |
| Where it counts | In-store and online, local and overseas |
| How you must pay | Google Pay on your phone (or Fitbit) |
| Crediting | Up to 30 days after VisaNet settles the transaction |
Cumulative is the important word. There's no minimum per transaction, so ₱3,000 can be eleven grocery runs, a month of coffee, one appliance, or any mix. You are not chasing a ₱1,000-per-swipe threshold the way you were in the August version of this promo.
The step everyone skips
You have to register on the Visa campaign page first.
This is not automatic. Having an RCBC Visa card in Google Wallet does not enrol you. Spending ₱3,000 without registering earns you exactly zero, and there is no retroactive fix once the promo closes.
Register first. Then spend. In that order.
The other trap: your physical card earns nothing
Only transactions made through Google Pay qualify. Tapping the plastic card itself — the same card, the same merchant, the same amount — does not count.
This trips people up because the payment feels identical at the terminal. Both are contactless. Both beep. But the promo is Google's user-acquisition budget at work: they are paying to get the card into your phone and to get you tapping with it. A physical card tap doesn't achieve that, so it doesn't earn.
So: add the card to Google Wallet, and actually pay with the phone.
What it's really worth
Here's the part worth sitting with. On ₱3,000 of spend you were going to do anyway — groceries, load, gas, the same things you buy every month — ₱1,500 back is a 50% return, and it lands in under a month.
For scale, put that against where else you could park ₱3,000:
| Where the ₱3,000 goes | Return | Time to earn ₱1,500 |
|---|
| This promo | ₱1,500 | ~3 weeks |
| A 6% p.a. digital bank | ₱180/yr, before the 20% tax | About 10 years |
| Pag-IBIG MP2 at ~7% | ₱210/yr, tax-free | About 8 years |
That comparison is a little unfair — the promo is one-time and capped, and you can't repeat it — but it makes the point. There is no savings product in the Philippines that competes with a one-off 50% cashback. If you were spending the money regardless, this is the highest-return thing you can do with it this month.
The word doing the heavy lifting is regardless. Cashback stops being a return the moment it makes you buy things you weren't going to buy. Spending ₱3,000 you hadn't budgeted to get ₱1,500 back means you're down ₱1,500, not up. The promo only works on spending that was already happening.
If you're not with RCBC
The Visa x Google Pay campaign has run through several issuers this year, with different mechanics:
- Maya Visa — ₱700 cashback for three separate transactions of at least ₱1,000 each via Google Pay. Both physical and virtual Maya Visa wallet cards now work with Google Wallet.
- Earlier RCBC round (August 2026) — ₱700 for three transactions of ₱1,000+, which is the per-transaction structure the current promo dropped.
- Pick Up Coffee — a free upsize when you pay with Visa, plus ₱50 off when you tap with Google Pay, across 100 participating stores.
Check your own issuer's promo page before assuming you're not covered. These campaigns rotate, and they are usually announced on the bank's site rather than pushed to you.
Worth doing, with the caveats stated
Register, add the card to Google Wallet, pay with your phone for the rest of September, stop caring once you've cleared ₱3,000. The cashback shows up within 30 days of settlement.
Two honest caveats. First, ₱1,500 is a hard cap per card — spending ₱9,000 does not get you ₱4,500, so there's no reason to push past ₱3,000 for this promo's sake. Second, depending on your card type the cashback may not be withdrawable as cash, and withdrawal fees can apply; for most people it simply reduces the next statement, which is fine.
If you want to see what your actual disposable income looks like before deciding how much of September's budget to route through this, the income tax calculator gives you the take-home figure. And if the ₱1,500 is going straight to savings rather than back into spending, the digital bank calculator shows what the 20% withholding tax does to interest once it's parked.
Sources